When a private company tied to a public official swings from a modest valuation to multimillions and then back to zero net value—followed by a corporate shutdown—the issue is not partisanship; it is governance. Valuation choices, liabilities, and corporate hygiene become matters of public trust when they show up on a congressional financial disclosure.
At a Glance
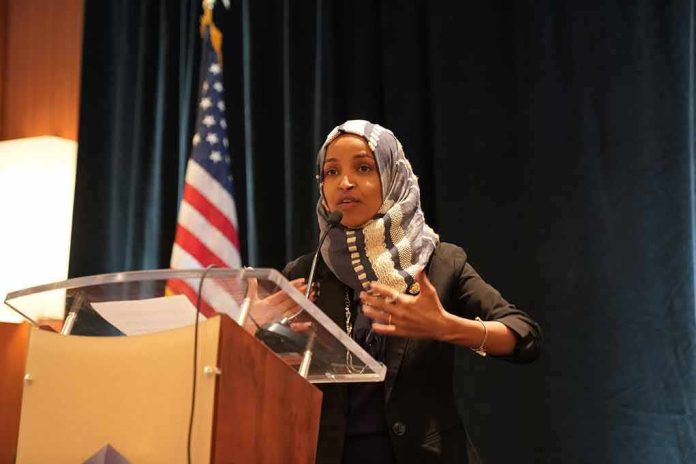
- House disclosures initially listed eStCru LLC, a Santa Rosa winery tied to Rep. Ilhan Omar’s spouse, in a $1–5 million value band, with the couple’s combined assets summarized as $6–30 million across two businesses.
- Amended disclosures reduced both eStCru and Rose Lake Capital to no net value after liabilities, shrinking the couple’s reported aggregate assets to roughly $18,004–$95,000, while still reporting some business income.
- Shortly after congressional records requests, eStCru was formally dissolved in California, cementing a chronology that has drawn intensified scrutiny.
- House Oversight Chair James Comer requested detailed records and communications; separate reporting describes prosecutorial review of the financial disclosures.
What the official record and contemporaneous reporting establish
The public record begins with the House financial-disclosure system, which requires members of Congress and their spouses to report assets in broad valuation bands rather than precise figures. In that framework, eStCru LLC—identified on a filed disclosure as a winery—was reported within a $1,000,001–$5,000,000 value range for 2024, up from a $15,001–$50,000 band the prior year; the same filing reflected a small amount of income attributed to the winery. Reporting at the time synthesized those ranges with the disclosed estimates for Rose Lake Capital, characterizing the couple’s combined assets across the two businesses as falling within a $6–$30 million spread.
That picture changed with amendments. The revised disclosures reduced eStCru and Rose Lake Capital to no net value after liabilities and recalculated the couple’s overall reported assets into a far lower range—roughly $18,004–$95,000—while still acknowledging some income, including a few thousand dollars from eStCru. These revisions are central because they convert the narrative from one of sudden wealth to one of debt-adjusted worth. Omar’s spokesperson and attorney, in various accounts, attributed the earlier, higher numbers to accounting errors—specifically, reporting gross assets without offsetting liabilities—and said the amendment was a voluntary correction made when the discrepancy was caught.
Why the dissolution matters—and what it does not prove
The timing of eStCru’s end heightened interest. House Oversight Chair James Comer wrote on February 5 requesting financial records and communications concerning eStCru and Rose Lake Capital after the valuation changes surfaced. Within weeks, California records showed eStCru filed dissolution paperwork. Coverage places the shutdown either roughly two months after Comer’s letter or nine days after the amended disclosure hit the Clerk’s site; either way, the closure followed hard upon the requests and revisions. This sequence does not, by itself, establish cause and effect, but it does define a clear investigative timeline anchored in public filings and state records.
Comer’s request framed a concrete inquiry, not merely a rhetorical objection to valuation swings. He asked for records that would reconcile ownership interests, liabilities, and valuation bases—exactly the material that would explain how a private entity could appear in a seven-figure band one month and zero-out after debt the next. Separate coverage has described prosecutorial interest in the disclosures, signaling that at least some authorities view the paper trail as worthy of review, though an inquiry is not a finding. One brief caveat belongs here: an investigation or request for records does not, by itself, prove misconduct.
How congressional disclosures create confusion around private-company values
The House system is designed for transparency through ranges, not for forensic accounting. Private-company entries can reflect an ownership stake, a fair-market estimate, or even a gross asset tally—none of which automatically equates to realizable equity. When liabilities are large or when valuation methodology changes, a move from a multimillion-dollar band to zero net value is arithmetically possible without implying fabrication. The disclosure form itself does not force filers to attach workpapers, appraisals, or debt schedules, leaving readers to infer the bridge between gross and net from terse line entries.
That structural opacity is why investigators typically ask for the underlying ledgers: general journals, bank statements, tax returns, capitalization tables, and contemporaneous valuations. Only those records reconcile what was reported with how it was computed and whether the filer followed the form’s instructions. The Oversight Committee’s request tracks that logic, seeking source documents that can confirm whether the original valuation reflected gross assets, an ownership share applied to an enterprise value, or another basis entirely.
The empty-barrel narrative versus the established record
The most sensational claim circulating around eStCru alleges investors were sold empty barrels. The materials that anchor this article—House disclosures, public amendments, a records request from the Oversight Committee, and state dissolution filings—do not resolve that allegation. What they do establish is a documented valuation swing, a rapid amendment to no net value after accounting for liabilities, a request for corroborating records, and a subsequent corporate shutdown. Those facts justify scrutiny; they do not, standing alone, adjudicate what investors received or whether inventory matched marketing.
It is worth understanding why wine investments draw attention: the sector has seen real fraud cases in which promoters misrepresented ownership of bottles, provenance, or storage, prompting SEC actions against firms like Windsor Jones and Charles Winn for deceptive wine investment schemes. That history explains why a winery’s valuation and inventory representations invite detailed verification. But precedent is context, not conclusion; each enterprise turns on its own ledgers, contracts, and physical stock.
To deep-dive clarify, if you’re interested:
it’s worth noting that James Comer is the House oversight committee chairman. He has access to sources other than public media reports, so there’s that.
Comer said on Fox News this week that Ilhan Omar’s wine operation called eStCru…
— Morning Song (@MorningSongMN) October 19, 2026
What a competent inquiry would test next
If you want resolution—beyond headlines and counterstatements—you follow the books and the barrels. The documentary spine starts with the original and amended House disclosures and the instructions that governed valuation; then the company’s general ledgers, bank statements, tax returns, debt schedules, and capitalization tables to rebuild net equity at each reporting date. Contracts with investors, subscription agreements, invoices, wire confirmations, and marketing decks establish what was promised and paid. Production records—bonded-winery filings, tank logs, bottling runs, storage manifests, and excise-tax filings—corroborate whether volume and inventory claims were physically supported. That is the work of weeks, not days, but it is finite and testable.
Two outcomes are common in cases like this. One, the amended filing reflects a bona fide correction—perhaps liabilities that swamped asset value or a shift from enterprise value to net equity—making the original entry sloppy but not sinister. Two, the paper trail shows inconsistencies between what investors were told, what disclosures reported, and what the company actually owned or produced, inviting civil or criminal exposure. The Oversight Committee’s targeted records request is structured to distinguish between those paths.
Why this matters beyond one member’s file
Congressional disclosures are among the few standardized windows into the financial lives of federal lawmakers and their spouses. When a disclosure swings into eight figures and then recedes to five after an amendment, the public needs to know whether the delta was debt, error, or misrepresentation. The answer shapes more than a single headline: it informs how much confidence to place in a transparency regime that relies on filer candor, broad ranges, and post hoc corrections. It also influences how Congress calibrates oversight when private ventures overlap with public power—especially in sectors, like alternative assets and niche agriculture, where valuation is as much craft as science.
Sources:
twitchy.com, dallasexpress.com, newsweek.com, theepochtimes.com, timesnownews.com, disclosures-clerk.house.gov, legalinsurrection.com, academic.oup.com